

Allocating Facebook Advertising Budgets When a Business Has Multiple Product Groups

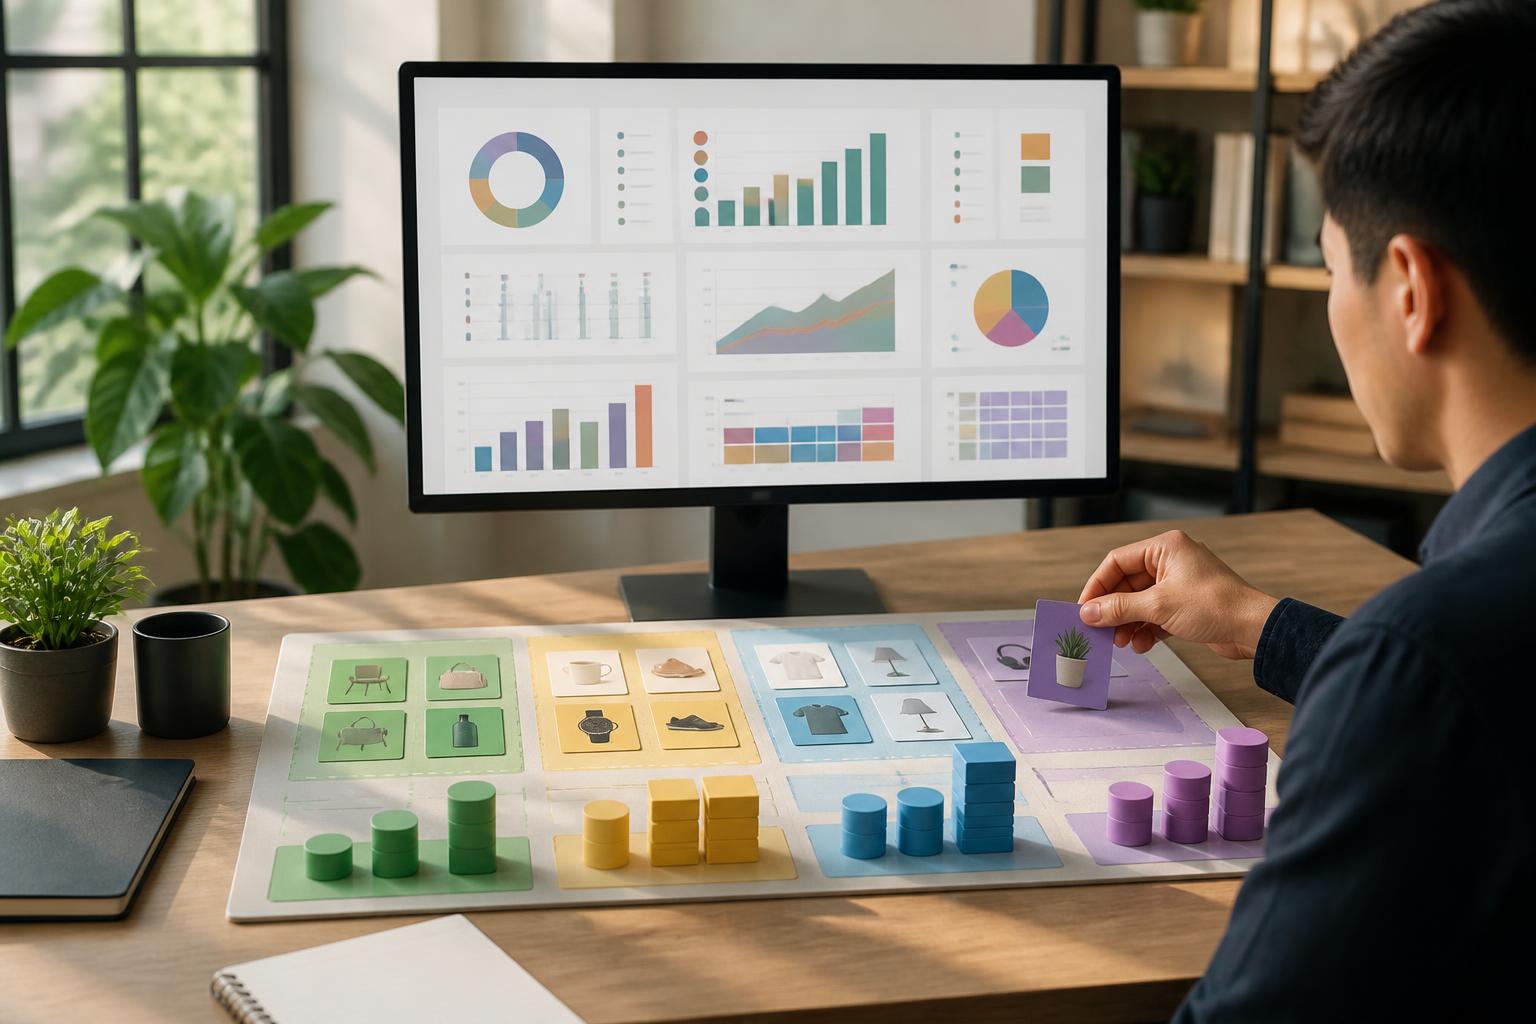
When a business sells only one product or serves a relatively homogeneous customer group, setting a Facebook advertising budget is usually fairly straightforward. However, the challenge changes quickly when the catalog expands to include multiple price points, different sales seasons, and various business objectives. One product may generate many orders but have a low profit margin, while another may generate fewer orders but bring in much higher value. If the budget is divided based on intuition or split evenly among all product groups, the account can easily end up with campaigns that spend money without making a significant contribution to profit.
Proper budget allocation is not only a decision about how much to spend on each campaign. It is also the process of determining which products should be prioritized, which customer groups are worth investing in, when spending should be increased or reduced, and what thresholds require the business to intervene. A good budgeting system must be flexible enough to seize opportunities while having clear limits to prevent an advertising group from spending beyond its profit-generating capacity.
Start with business objectives instead of looking only at advertising costs
Many accounts are managed based on a single question: which campaign has the lowest cost per result? This metric is useful, but it is not enough to determine the budget. A low-priced product often generates purchases or registrations more easily than a high-priced product, but that does not mean the low-priced product always deserves a larger share of the budget. Before dividing the funds, the business needs to define the primary objective for each product group.
For a core product, the objective may be to expand revenue while keeping profit within an acceptable range. For a new product, the initial objective may be to test demand and collect data, without necessarily maximizing sales immediately. Another product group may be used to increase order value through cross-selling or to expand the existing customer base. Once the objective is clear, the evaluation metrics must also change accordingly. A test campaign should not be stopped too early simply because it has not achieved the same performance as a campaign with stable historical data.
The business should create a simple table for each product group, including expected revenue, profit margin, average order value, cancellation or return rate, supply capacity, and advertising objective. This table helps make budget decisions that are closer to operational reality, rather than relying solely on the numbers displayed in Ads Manager.
Allocate the budget according to each product’s role in the catalog
A practical approach is to classify products by role before allocating funds. The first group consists of flagship products with clear demand and stable supply capacity. This group is generally suitable for ongoing and expansion budgets, but it still needs a control threshold for conversion costs or profitability.
The second group consists of complementary products. These products may not generate much revenue independently, but they help increase basket value or improve the performance of the main product. Advertising for complementary products should be considered alongside overall purchasing behavior. If each product is measured separately, the business may underestimate their role.
The third group consists of experimental or seasonal products. The budget for this group should be limited to an amount the business can accept losing in exchange for information. The objective of the testing phase is to identify potentially effective messaging, content formats, customer segments, and price points. Once reliable signals have been obtained, the product can be moved into the group requiring long-term investment.
The final group consists of products with low profitability, unstable supply, or strong dependence on timing. Not every product needs to be advertised continuously. During certain periods, the most reasonable use of the budget may be to pause promotion and only maintain cross-selling activities or serve demand from customers who already know the brand.
Set a base budget and an opportunity budget
Instead of putting the entire budget into currently running campaigns, the business can divide it into two parts. The base budget is allocated to products and customer groups that need to be maintained consistently. This amount prevents advertising activity from being interrupted abruptly and makes it possible to compare results across relatively stable periods.
The opportunity budget is held back to respond to special situations, such as when a product’s content is receiving good feedback, a sales program is about to take place, or a new customer group shows positive signals. This reserve should not be used arbitrarily just because results are good for a few days. The business needs to establish clear conditions before releasing the funds; for example, the signal must appear across multiple ad groups, the landing page must still be able to meet demand, and the sales team must be capable of handling the increase in customers.
This division also helps avoid a common mistake: increasing the budget too quickly for a campaign that has just produced good results. If all the money is pushed into one product group, fluctuations in demand, advertising quality, or delivery capacity can immediately affect the entire account.
Evaluate performance based on contribution profit
To allocate the budget more accurately, the business needs to go beyond metrics such as impressions, clicks, and cost per result. An order is meaningful only when the revenue remaining after the cost of goods, operating expenses, promotions, payment fees, delivery costs, and advertising still reaches an acceptable level.
The business can determine a maximum advertising cost threshold for each product group based on its actual profit margin. This threshold does not necessarily have to be the same across products. A product with high customer lifetime value may be able to tolerate a higher initial cost, while a one-time purchase product with little likelihood of repeat business needs tighter control.
Results must also be distinguished according to the sales model. If advertising generates orders directly on the website, the data can be reconciled with actual revenue received. If advertising generates messages or leads, the evaluation must include the response rate, successful consultation rate, closing rate, and post-sale revenue. The entire budget should not be shifted to a campaign simply because its cost per message is low if the consulting team cannot turn those conversations into business opportunities.
Rules for increasing, reducing, and stopping the budget
The budget needs specific operating rules to reduce dependence on the manager’s perceptions. When a campaign achieves its target over several consecutive evaluation cycles, shows sufficiently stable conversion signals, and has no inventory or order-processing issues, its budget can be increased incrementally. Increasing it in stages allows the business to observe whether performance can be maintained.
Conversely, a campaign should not have its budget reduced simply because it performs poorly on one day. A sufficiently long period should be considered to avoid reacting to short-term fluctuations. However, if costs rise while customer quality declines, the content loses its appeal, the landing page has problems, or the sales team responds slowly, the budget should be adjusted sooner rather than waiting until the loss becomes obvious.
Stopping a campaign should also have a documented reason. This could be that the product is out of stock, the profit margin has changed, the customer segment has become saturated, the messaging is no longer appropriate, or costs have exceeded the threshold across multiple evaluations. Recording the reason helps the business distinguish between a campaign that needs optimization and one that is genuinely no longer suitable.
Coordinate the budget across product groups
Product groups do not exist independently. An advertisement for a low-priced product may introduce customers to the brand, after which the business can sell them a higher-value product. Therefore, when considering budget allocation, the relationships between campaigns need to be examined. If two groups target the same customer segment while competing directly, costs may increase and the data may become difficult to interpret.
The business should determine which product groups can share content, which require separate messaging, and which should be approached at a later stage of the buying journey. This separation does not necessarily require creating a large number of campaigns. What matters is that the structure is clear enough to show what objective the budget is serving, while not fragmenting the data to the point that each group lacks sufficient information for evaluation.
In addition to advertising data, information from inventory, customer service, and sales should be incorporated into budget decisions. A campaign may be performing well on the platform but placing pressure on delivery operations or forcing the business to sell products at excessively high discounts. Advertising performance is meaningful only when it aligns with the entire operational chain.
Periodic budget review process
Each review cycle should begin by comparing the planned budget with the actual budget. The business then examines results for each product group, conversion quality, contribution profit, and factors outside advertising such as selling price, inventory, or order-processing speed. Changes in content and customer segments should also be noted to avoid drawing conclusions without context.
At the end of each cycle, answer four questions: which group is currently creating the most value, which group needs support rather than simply more money, which group should receive less investment, and whether the reserve budget needs to be used. If there is not enough data to draw a conclusion, keep the budget at a controlled level and continue gathering information instead of making major changes.
Effective Facebook advertising budget allocation is not about finding a fixed ratio and applying it forever. It is a continuous decision-making system in which the budget is shifted according to product role, actual profitability, customer quality, and the business’s capacity to serve customers. When these principles are documented as a process, the account becomes less dependent on short-term fluctuations and has a stronger foundation for expanding investment.